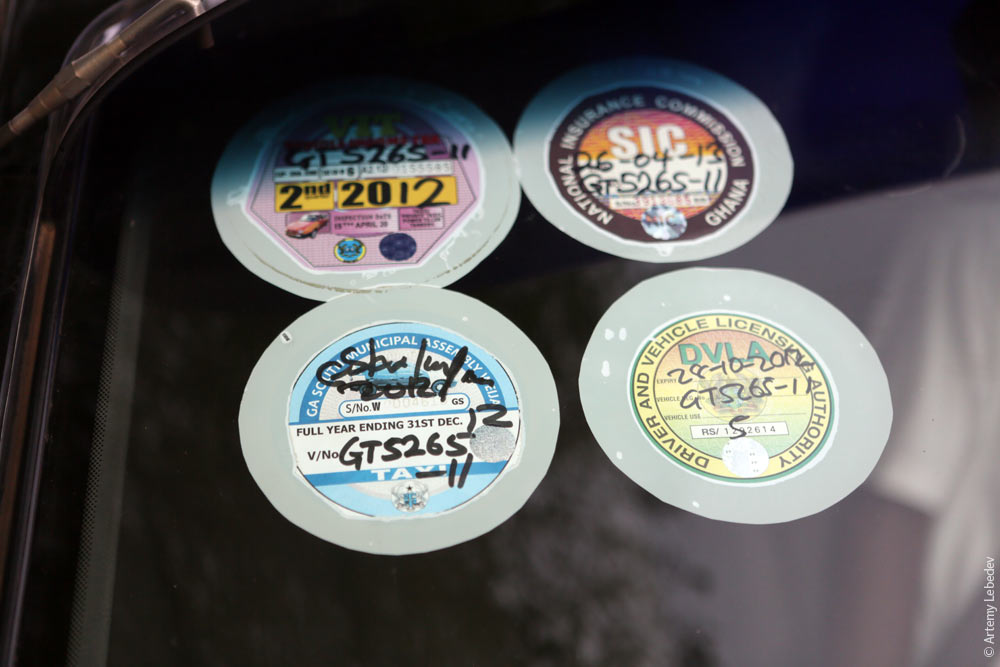
National Protocol Director of the New Patriotic Party (NPP), Kwadwo Afari, has called for the abolition of compulsory third-party motor insurance in Ghana. He is arguing that the country must reconsider whether the existing system remains the most effective and accountable means of compensating victims of road accidents.
In an article titled “The Case Against Compulsory Third-Party Insurance,” Mr Afari said although the policy was introduced to protect innocent victims of road crashes, persistent concerns over delayed, disputed and denied insurance claims had raised questions about its effectiveness.
Afari maintained that the objective of ensuring compensation for accident victims was not in dispute, but argued that the means of achieving that objective required a thorough national review.
“Every vehicle owner in Ghana is legally required to purchase third-party motor insurance before using a public road,” Afari noted, explaining that the policy was intended to ensure that victims of accidents caused by negligent drivers could obtain compensation for injuries, deaths and property damage.
However, he questioned whether the state should continue to use criminal sanctions to compel citizens to purchase a financial product from private insurance companies.
According to Afari, motorists who fail to obtain the required insurance may face fines, prosecution, vehicle impoundment and other sanctions, even when they have not caused an accident or injured anyone.
He argued that the justification for such enforcement measures deserved closer examination, particularly when concerns remained about the performance of the system that motorists were legally required to finance.
“The legitimacy of any compulsory system depends not only on its intentions but also on its performance,” Afari stated, adding that citizens compelled by law to purchase a product should be entitled to expect efficiency, transparency and fairness.
Proposed road-user compensation fund
As an alternative to the existing arrangement, Afari proposed the establishment of a road-user compensation fund financed through a modest levy on fuel.
He explained that such a model would link contributions to road usage, with motorists who consume more fuel contributing more to the fund, while those who drive less would pay comparatively less.
Under the proposed arrangement, the fund could be managed by the National Insurance Commission or an independent statutory authority, with its primary responsibility being the prompt and reliable compensation of road accident victims.
Afari said the proposal was not intended to undermine the insurance industry but to encourage a system that placed greater emphasis on accountability and the delivery of compensation.
He acknowledged that replacing compulsory third-party insurance with a publicly administered compensation mechanism would require careful actuarial analysis, consultations with stakeholders and legislative review before implementation.
Insurance industry must compete on service delivery
Afari also argued that the current compulsory insurance regime provides private insurers with a guaranteed market because vehicle owners are legally required to purchase third-party cover.
He suggested that this arrangement could weaken some of the competitive pressures that would ordinarily encourage companies to improve their services and respond more effectively to customers.
According to him, transferring basic third-party compensation to a dedicated fund could encourage insurers to compete more vigorously in other segments of the market, including comprehensive motor insurance, life insurance, health insurance and business insurance.
He said insurers would then have stronger incentives to attract and retain customers through faster claims processing, improved customer service, innovative products and competitive pricing.
Afari maintained that greater competition could improve efficiency across the industry and encourage investment in new insurance products and services.
He stressed, however, that the proposed reform should not be interpreted as a call to abandon accident victims or weaken their right to compensation.
“This is not a call for the immediate abolition of compulsory third-party insurance,” Afari stated in his article. “What should be abolished is not compensation for accident victims, but the legal requirement that citizens purchase compensation through private insurers.”
Calls for comprehensive national review
Afari called on the Ministry of Finance, the National Insurance Commission, the Ghana Insurers Association, road-safety authorities, consumer groups and Parliament to undertake a comprehensive review of the country’s third-party motor insurance framework.
He proposed that an independent study, parliamentary inquiry or carefully designed pilot programme could help determine whether alternative compensation arrangements would better serve motorists, accident victims and taxpayers.
He further argued that the burden should be on the state to demonstrate that the existing system continues to serve the public effectively, fairly and transparently.
According to Afari, a national review would be beneficial even if it ultimately confirmed that compulsory third-party insurance remained the most suitable mechanism for protecting accident victims.
He said such an exercise would help strengthen public confidence in the system and identify areas requiring improvement.
Questions criminal penalties for uninsured motorists
A central part of Afari’s argument is the distinction between causing harm on the road and failing to purchase an insurance policy.
He contended that criminal penalties should be directed at motorists who cause injury and damage rather than automatically targeting citizens whose failure to obtain insurance does not, in itself, establish that they have harmed another person.
Afari questioned why a person should be stopped, fined, detained or deprived of liberty for failing to purchase insurance from a private provider, insisting that the state must justify the necessity and proportionality of such measures.
He argued that a law requiring motorists to make compulsory payments should not be shielded from public scrutiny simply because it had existed for decades.
“The real issue is not whether accident victims deserve protection. They unquestionably do,” Afari stated. “The real issue is whether citizens should be compelled to finance a system simply because it has always existed, or because it continues to deliver the best results.”
He urged policymakers to approach the matter as an opportunity to reconsider how Ghana can protect road accident victims while promoting fairness, transparency and accountability.
Afari concluded that the country must be prepared to examine alternative arrangements if evidence shows that they could deliver better outcomes for the public.
He posed a question he believes every motorist should be entitled to ask: “Does this system still serve the public, or has the public merely been conditioned to serve the system?”
He maintained that Ghana should be willing to reform the existing framework if a more effective and accountable mechanism for compensating accident victims can be established.